
Payday Advance Borrow Money
- Rating
- 4.7
- Downloads
- 100.00K
- Content Rating
- Everyone
Payday Advance Borrow Money - Screenshots
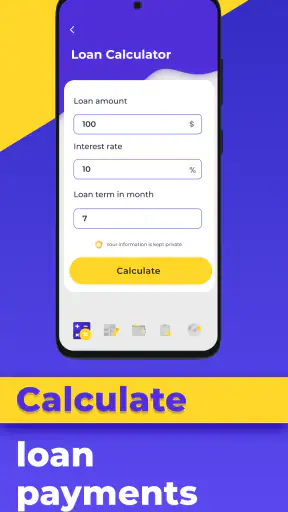
Pros
- Fast application process with clear borrowing steps
- Useful for covering unexpected short-term expenses
- Repayment details are shown before accepting an offer
- Accessible to users with limited traditional credit options
- Mobile interface makes account management convenient
Cons
- Advance fees can make the total repayment expensive
- Short repayment periods may strain already tight budgets
- Approval and terms may vary by applicant and location
- Late repayment could lead to additional charges or collection contact
- Requires sharing sensitive personal and financial information
Payday Advance Borrow Money - Description
- App Name
- Payday Advance Borrow Money
- Package Name
- com.bad.credit.payday.loans.easy.fast.safe
- Developer
- Shpuryk Sergii
- Category
- Finance
- Last Updated
- Nov 28, 2022
- Version
- 1.2.1
Payday Advance Borrow Money is a finance app aimed at people looking for a short-term cash advance. I approached it as a practical tool rather than a complete money-management service, and that distinction matters. Its purpose is narrow: help you look for a suitable payday advance from a phone. If you are facing an urgent bill and want to examine borrowing options without visiting a branch, the app may feel more convenient than traditional alternatives. If you are trying to build savings, compare long-term loans, or understand your overall financial health, you will probably need something broader.
The app is free to install, carries an Everyone age rating, and is developed by Shpuryk Sergii. It has reached over one hundred thousand installs and holds a 4.7 average from around three thousand ratings, with close to two hundred written reviews. Those figures suggest that many people find the basic experience approachable, but they should not be mistaken for a guarantee that every user will receive an advance or find suitable terms. A finance app can simplify the search while the actual borrowing decision still depends on the lender, eligibility checks, and the details shown during the process.
How the app works for different users and situations
Readability and navigation during a stressful search
My first impression is that the app’s value comes from reducing the number of steps between a financial need and a possible cash-advance option. That is useful when you are dealing with an unexpected expense and do not have the patience to browse several unrelated services. The focused purpose also makes it easier to understand what kind of task the app is designed for: this is about finding payday borrowing, not managing investments, tracking spending, or replacing a bank account.
That narrow focus can be helpful for people who prefer a direct interface. Someone who is comfortable reading ordinary financial prompts on a phone should be able to approach the process without learning a complicated budgeting system first. I also see an advantage for users who become overwhelmed by apps that combine credit cards, savings, insurance, rewards, and account analytics on one screen. Here, the central question remains whether a cash advance may fit the immediate need.
At the same time, financial clarity is more important than visual simplicity. A short form or a clean sequence does not automatically make borrowing easy to understand. I would slow down at every point where the app presents lender information, repayment expectations, eligibility questions, or any request for personal details. Readability is not only about large text or uncluttered screens; it is also about whether I can distinguish an application step from an approval, and an advertised possibility from a firm offer.
For users with dyslexia, limited reading fluency, or difficulty processing dense financial language, the safest approach is to read one screen at a time and avoid rushing through repeated prompts. I would keep a note of the amount requested, the expected repayment date, and every cost shown before continuing. If the wording is unclear, that is a reason to pause rather than assume the most favorable interpretation.
The app is also more manageable when used with a simple personal checklist. Before opening it, I would write down the exact amount needed and the date on which repayment could realistically be made. This prevents the search from turning into a vague attempt to borrow “as much as possible.” It is a small workflow improvement, but it is especially useful for anyone who finds financial decisions harder when tired, anxious, or distracted.
Motor and sensory considerations on a phone
Because this is a mobile finance app, the experience depends on ordinary phone interaction: tapping controls, entering information, scrolling, and reading confirmation details. That may suit people who prefer a handheld device to a desktop website, particularly when they need to check an option privately. It can also be more comfortable for users who already rely on phone-level settings such as enlarged text, display zoom, contrast adjustments, or a screen reader.
I would not assume that every control will work perfectly with every accessibility setting. The safest way to judge the experience is to test it on your own device before beginning a real application. Increase text size if needed, rotate the phone only if the screen remains understandable, and check whether important explanations stay visible when the display is enlarged. If a button becomes difficult to identify or a critical sentence is cut off, continuing may create avoidable mistakes.
Users with limited dexterity may benefit from taking the process slowly rather than trying to complete it with one hand while moving around. A stable surface, good lighting, and deliberate taps are more important here than speed. I would also avoid submitting information while traveling, standing in a queue, or handling another task. A mis-tap in a finance workflow is more consequential than a mis-tap in a casual game.
For people with low vision, audio dependence, or color-vision differences, the key issue is whether the information remains understandable without relying on color alone or on tiny text. I would look for clear labels, review screens, and written explanations rather than interpreting a green or red indicator as the whole meaning. If you use assistive technology, check each stage carefully, especially fields that may contain financial terms or confirmation actions.
Users with hearing loss are unlikely to need audio to understand the basic purpose of a written finance workflow, but any alert or spoken instruction should never be treated as the only important source of information. Keep an eye on the screen and review written details. Conversely, users who find reading difficult should consider whether a trusted person can help interpret the terms without taking control of the decision.
Situational access when time, privacy, or connectivity matters
The strongest practical case for Payday Advance Borrow Money is an urgent but controlled search. Imagine a household facing an unexpected bill shortly before payday. The person may not want to travel to a branch, may have limited time during a work break, and may need to compare a possible short-term option from a phone. In that situation, a focused app can be easier to approach than calling several providers or navigating unrelated banking products.
However, urgency can also reduce accessibility. A person under financial pressure may skim, overlook a repayment condition, or confuse a preliminary result with money already available. My advice is to separate the search from the final decision. Use the app to identify what may be available, then take a short pause and check whether the repayment date fits the next pay cycle. If the answer is uncertain, the app has still served as a search tool, but borrowing may not be the right next step.
Privacy is another situational concern. A phone can be more discreet than a public computer, yet a shared device, visible notifications, or an unlocked screen can expose sensitive financial activity. I would use the app in a private place, avoid saving personal details on a device used by several people, and close the session when finished. These are sensible habits for any finance service, but they matter more when the purpose involves short-term borrowing.
People with inconsistent internet access may find a mobile workflow convenient when a connection is available, but they should not begin an important submission if they expect interruptions. A dropped connection can leave you unsure whether a step was completed. I would use a reliable connection, keep any reference information displayed by the app, and avoid pressing a submission control repeatedly if the screen seems slow. The goal is to prevent duplicate actions and confusion.
The app may also suit users who need a quick first look outside normal branch hours, but convenience should not be confused with immediate access to funds. The presence of a potential advance does not itself resolve eligibility, approval, timing, or repayment. That is one of the most important distinctions I would explain to a friend before recommending it.
Where the app fits beside familiar alternatives
Compared with visiting a bank branch, the app is more private and flexible for an initial search. You can examine the possibility of a payday advance from a phone instead of arranging a meeting. Compared with a general banking app, it is more specialized, because ordinary banking tools usually focus on balances, transfers, and established accounts rather than helping users look for a short-term cash advance.
Compared with a budgeting app, this product addresses an immediate borrowing question rather than the causes behind a cash shortage. A budgeting tool may be better if your main need is to identify recurring expenses, plan bills, or build an emergency fund. Compared with a direct lender’s own application, a focused advance-search app may feel like a more convenient starting point, while the lender’s service may provide more direct information once you already know whom you want to contact.
That comparison leads to a useful rule: use this app for discovery, not as your only financial safeguard. I would not rely on it to decide whether borrowing is affordable. I would compare the total repayment with the amount received, check the timing against my income, and consider whether a payment arrangement, employer advance, credit-union product, or help from a trusted person would create less pressure. The best alternative depends on the situation, but a payday advance should not be the automatic answer simply because it is easy to investigate.
Remaining barriers and points that deserve caution
The main barrier is not necessarily navigation; it is the difficulty of making a sound decision while under pressure. Short-term borrowing can look manageable when viewed as a single amount, yet the repayment date may arrive before other essential expenses are covered. I would treat the app as unsuitable if paying back the advance would require another advance, skipping necessities, or relying on uncertain income.
Another barrier is financial vocabulary. Even users who navigate phones easily can struggle with terms connected to borrowing. If you have limited language proficiency, cognitive fatigue, or difficulty comparing numbers, ask someone you trust to read the details with you. Do not share passwords or allow another person to make the decision on your behalf merely because the process feels complicated. Assistance should improve understanding, not remove your control.
There is also a difference between accessibility and suitability. A person may be able to open and use the app but still be poorly served by its purpose. Someone looking for a long repayment period, a detailed credit-building plan, or face-to-face guidance should probably choose a different financial route. The app is also a weak match for anyone who wants extensive spending analysis or a complete view of their debts, because its focus is the cash-advance search rather than broader financial planning.
I would be particularly cautious about entering information before understanding why it is requested and what stage of the process I have reached. Keep screenshots or written notes only if doing so is safe on your device, and review any final screen before confirming. Never assume that a high user rating means the same outcome will apply to your circumstances. Ratings can indicate that people found the app usable, but they cannot predict approval or affordability.
The current version is 1.2.1 and supports devices running Android 5.0 or later. That broad operating-system reach is useful for people who keep an older phone rather than upgrading frequently. Still, an older device may have a smaller display, slower performance, or limited support for newer phone accessibility settings. I would test the app with the exact device and display configuration I plan to use, especially before entering sensitive information.
My inclusive verdict
After looking at it through the needs of different users, I see Payday Advance Borrow Money as a focused and potentially convenient starting point for exploring short-term cash advances. Its free entry, finance-specific purpose, and mobile format can help people who need a private first step and prefer not to visit a branch. The Everyone rating also makes it broadly approachable from an age-classification perspective, although that does not remove the need for careful financial judgment.
The most important accessibility feature is the time you give yourself to understand the borrowing decision. Larger text, a quiet room, a steady connection, and help from a trusted person can make the process easier, but none of those supports can turn an unaffordable advance into a safe one. I would use the app only after writing down the amount needed and the realistic repayment date, then compare the result with less costly alternatives.
My recommendation is therefore conditional. I would suggest it to a friend who needs a convenient way to investigate a payday advance and can independently read, compare, and repay the terms. I would not suggest it as a first choice for someone already juggling several debts, someone who needs long-term financial guidance, or anyone whose income timing makes repayment uncertain. In those cases, a nonprofit adviser, local credit union, bank conversation, or budgeting service may offer better support.
For a narrowly defined search, Payday Advance Borrow Money is easier to understand than a general-purpose finance app because it keeps attention on one immediate task. Its developer, Shpuryk Sergii, has created a tool that may be useful when speed and phone access matter. Just remember what it is: a way to explore a possible cash advance, not a promise of approval, a substitute for financial planning, or proof that borrowing is affordable.
If you can use the app calmly, protect your privacy, and verify every repayment detail before proceeding, it can be a practical addition to your search. If accessibility needs, language barriers, or financial stress make those checks difficult, pause and bring in human support. That extra step may take longer, but for this kind of decision, clarity is more valuable than speed.
FAQ
What is Payday Advance Borrow Money, and how does it work?
Payday Advance Borrow Money is a financial app designed to help eligible users request a short-term cash advance through their mobile device. After creating an account and providing the requested personal and financial information, the app may evaluate your application and display available options. Approval, loan amounts, repayment dates, and funding speed depend on the provider, your eligibility, and applicable local regulations.
Is Payday Advance Borrow Money a direct lender?
Not necessarily. Apps with this type of name may operate as loan-matching services or connect users with third-party lenders rather than providing the money themselves. Before accepting an offer, carefully check the lender’s identity, annual percentage rate, finance charges, repayment schedule, late fees, and privacy policy. Do not assume that an application guarantees approval or that every displayed offer comes from the app developer.
How much does borrowing through the app cost?
The total cost can vary significantly depending on the lender, loan amount, repayment term, state or country, and your credit profile. Possible charges may include interest, origination fees, subscription fees, expedited-transfer fees, or late-payment penalties. Review the full agreement before accepting anything, paying particular attention to the APR and the total amount you will repay. Avoid proceeding if the costs are unclear.
What information does the app require, and is my data safe?
A payday advance application may request details such as your name, address, phone number, employment information, income, bank account, and identity documents. These details can be sensitive, so download the app only from an official store and review its permissions and privacy policy. Confirm who receives your information, how long it is retained, and whether it is shared with lending partners or marketing services.
What should I consider before taking a payday advance?
A payday advance can provide quick access to emergency funds, but it may be expensive and difficult to repay if your next paycheck cannot cover the balance. Before applying, compare the offer with alternatives such as a bank or credit-union loan, an employer advance, or assistance from a trusted organization. Make sure you understand the repayment date and never borrow more than you can realistically repay.


